Buying your first home is exciting, and it can also feel like a lot of unknowns at once. The good news is that the process follows a fairly predictable order. Here's how I'd suggest approaching it.
1. Get clear on your budget
Your budget is more than the purchase price. Think about your deposit, legal fees, any building or other reports, moving costs, and the ongoing costs of owning a home such as rates, insurance and maintenance. Knowing all of that early stops surprises later.
Costs that tend to catch first home buyers out include:
- Your lawyer's fees
- A building report and a LIM report
- Any valuation or fees your lender charges
- Home insurance, which you'll want arranged in time for when the risk of the property passes to you (ask your lawyer when that is)
- Rates and other adjustments that are settled with the seller on settlement day
- Moving costs, and the small things you'll need straight away
2. Talk to a lender or mortgage adviser
Pre-approval tells you how much a lender is likely to lend, so you can shop with confidence. It isn't a guarantee, and a lender will still check details once you've chosen a property, but it's the best first step. If you don't have a mortgage adviser, I'm happy to introduce you to one I work with.
Quick tip
Ask your lender and check official sources for any first home support you may be eligible for, including KiwiSaver options. The rules change, so always check what's current.
How much deposit do you need?
Many lenders like to see a deposit of around 20%, but that isn't the only way in. Some lenders will lend with a smaller deposit, usually at a higher interest rate or with extra conditions. Kāinga Ora's First Home Loan is designed for buyers with a 5% deposit, if you meet its income, price and location rules. You may also be able to use your KiwiSaver for a first-home withdrawal, generally once you've been a member for a few years.
Eligibility and limits change, so check what applies with your lender, your KiwiSaver provider and Kāinga Ora. I've also covered it in Do you need a 20 percent deposit? and KiwiSaver and first home help.
3. Write down your must-haves and nice-to-haves
It's easy to fall for a house that ticks the wrong boxes. Before you start viewing, list what you truly need (bedrooms, section size, location, warmth) and what would simply be nice. It makes comparing homes far easier and keeps you focused.
4. Find a lawyer early
Your lawyer reviews the sale and purchase agreement and helps you work through any relevant conditions. It's far better to have someone lined up before you find the house than to hunt for one in a hurry.
5. View plenty of homes and don't rush
Look at a range of properties, at different times of day if you can. You'll quickly get a feel for what's normal in your price range and what's good value.
What to look for in an Invercargill home
- Warmth. Southland winters are long, so insulation, a heat pump or other effective heating, and double glazing make a real difference to comfort and power bills. See keeping warm in Southland.
- Sun and shelter. A section that gets the sun and is out of the worst of the wind is easier to heat and nicer to live in.
- Condition and age. Look at the roof, the foundations, any signs of damp and the age of the wiring and plumbing. A building report puts that in writing.
- School zones. If you have, or plan to have, children, check the zones for your shortlist. My school zones map is a good place to start.
- Day-to-day fit. Think about the drive to work, the shops, the street at different times, and where you'd park.
My open home checklist is handy to have with you when you view.
6. Make an offer with the right conditions
Many offers include conditions, such as finance, a building report or a LIM. Once every condition is met, the agreement becomes unconditional and you move towards settlement.
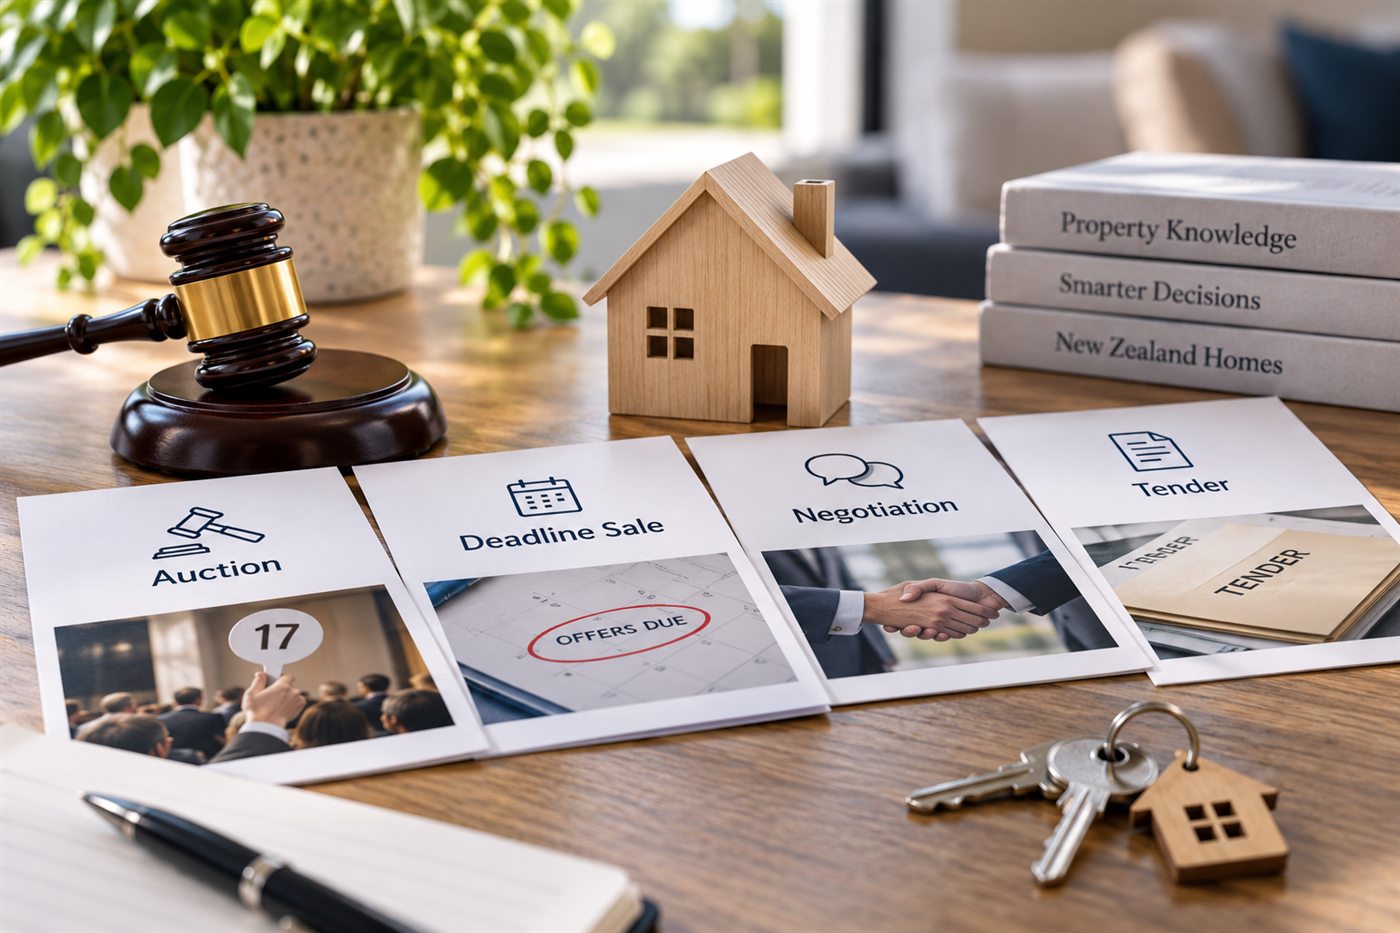
It also helps to know how the home is being sold, because it changes how you offer. A property can be listed with a price, or go to auction, a deadline sale, negotiation or tender, and each works differently. I've explained them in auction, deadline sale, negotiation or tender.
7. From unconditional to settlement
Once the agreement is unconditional, the sale is committed and the work shifts to getting you to settlement day, which is set in the agreement. During that time:
- Your lender finalises the mortgage and your lawyer prepares the settlement paperwork
- You arrange your insurance, so it's in place when you need it
- You do a pre-settlement inspection, usually a day or so before settlement, to check the home is in the condition you agreed to and that everything included in the sale is still there
- You line up power, internet and your moving plans
On settlement day your lawyer arranges the transfer of funds, and once it's confirmed you get the keys. The exact timing depends on your agreement, so your lawyer can tell you what to expect.
8. Moving in
Once you have the keys, there are a few small jobs worth doing early: find where the water shut-off and the switchboard are, check the smoke alarms, change the locks if you'd like to, update your address with your bank, employer and other providers, and keep the documents from the sale somewhere safe.
Common first-home mistakes
- Stretching the budget to the pre-approval limit, with nothing left for repairs or higher rates.
- Forgetting the running costs of owning a home, such as rates, insurance and maintenance.
- Skipping the building report because the home looks fine.
- Falling for the home before checking the numbers. It's easier to say no early than to unwind a purchase later.
- Leaving the legal side until the last minute. Have your lawyer ready before you make an offer.
Questions I'm often asked
How much can I borrow? A lender or mortgage adviser can tell you, and pre-approval makes it official. Your budget is what you're comfortable repaying, which is often less than the maximum.
Do I need my own lawyer? Yes. I'm always happy to guide you through the process, but a lawyer who acts only for you is an important part of your team, alongside your lender. They check the agreement, explain what you're agreeing to and protect your interests.
How long does it take? It varies. Some people find a home within weeks, and others look for months. Pre-approval, a lawyer and a clear list of what you need will save you time.
If you'd like a hand along the way, tell me what you're looking for and I'll keep an eye out for you through the Buyers Loop.
This is general information only, not legal, financial or building advice. Rules and market conditions change, so check the details with your lawyer, lender or the relevant authority before making decisions.