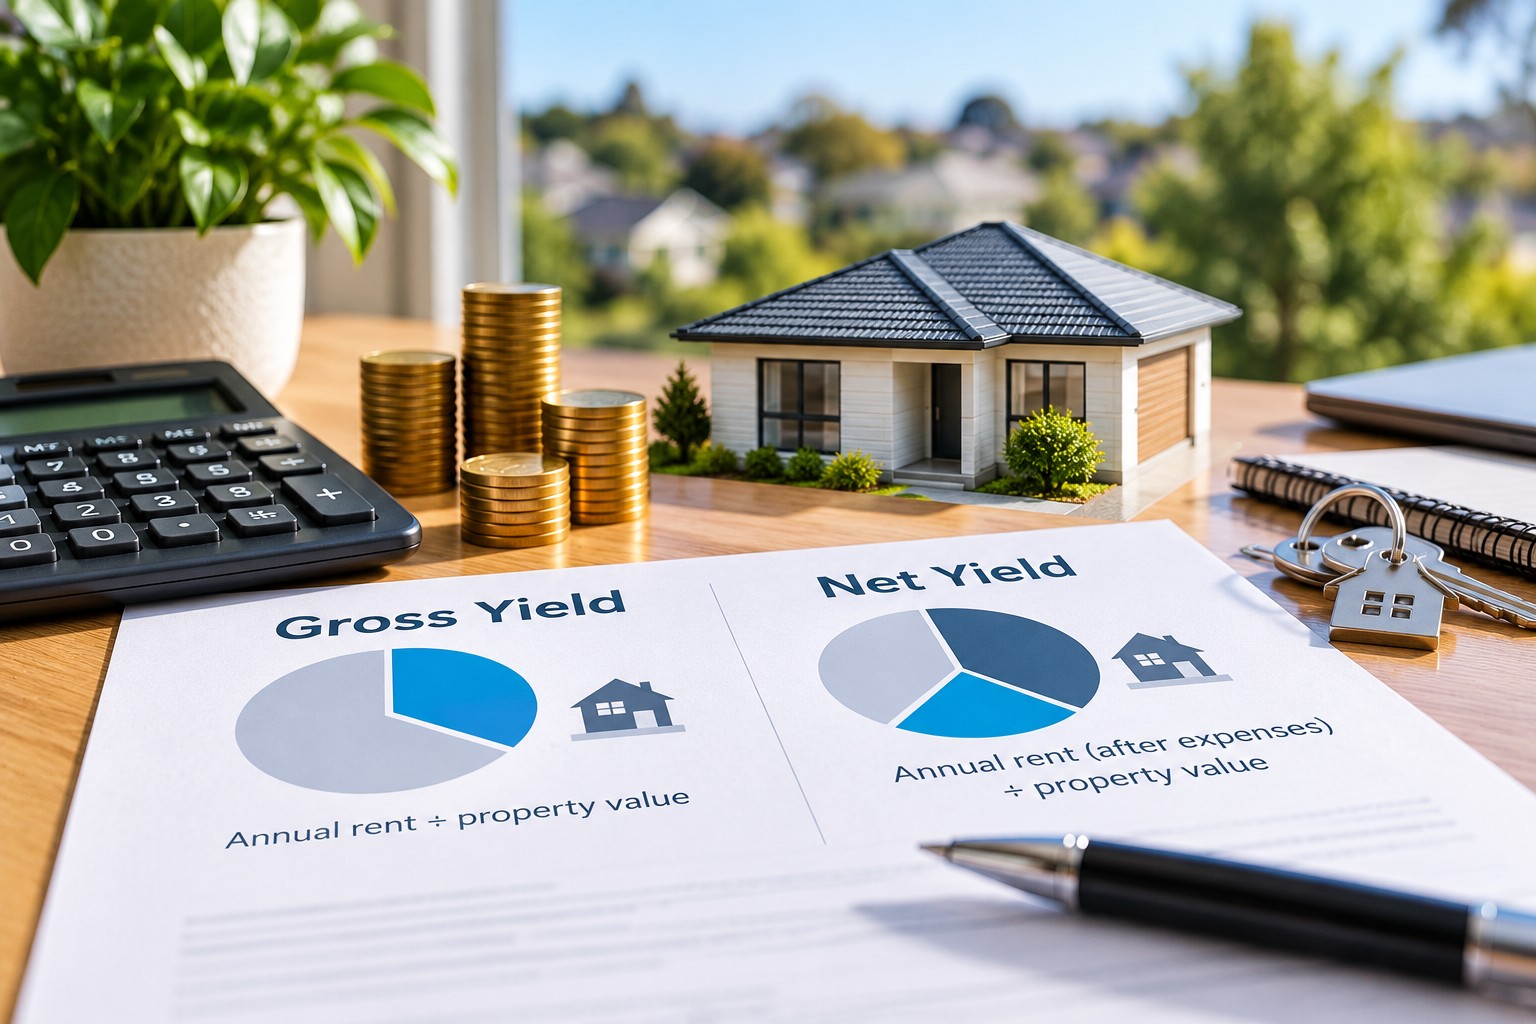
"Yield" gets thrown around a lot when a rental property is being sold, and it's usually the gross figure — the bigger, more flattering number. It's worth knowing the difference before you use it to compare properties or decide whether one actually stacks up.
Gross yield
The annual rent as a percentage of the purchase price, with nothing taken out. It's quick to calculate and useful as a first-pass comparison between properties, but it doesn't reflect what actually lands in your pocket.
Net yield
The annual rent minus your actual running costs — rates, insurance, maintenance, property management fees, body corporate levies if applicable, and a reasonable allowance for vacancy — expressed as a percentage of the purchase price. This is a much more honest picture of what the property is really returning.
Net yield is normally worked out before mortgage interest, because interest depends on how you've funded the purchase rather than on the property itself. Your own cash position, after interest, is a separate question, and it's worth working out too.
Two properties can show the same gross yield and have meaningfully different net yields, purely because one has higher rates, an older roof, or sits in a body corporate with high fees.
Try it with your own numbers
Put in a price, the weekly rent and your best guess at the yearly costs to see the gross and net yield side by side. Use the figures from a real listing and the gap is usually bigger than people expect.
Quick tip
If a listing or an agent quotes you a yield figure, ask whether it's gross or net — and if it's gross, ask for a rough expense breakdown so you can work out the net figure yourself.
Neither number tells the whole story on its own
Yield is a useful screening tool, but it doesn't account for capital growth, tax position, or how a property fits your broader strategy. A lower-yielding property in a strong growth area can still be the better long-term decision. Yield is a starting question, not the final answer.
Happy to talk through the actual numbers on a specific property with you, gross and net both.
This is general information only, not financial or investment advice. Speak with your accountant or financial adviser about your specific numbers.