Two words come up in almost every conversation about investing: equity and leverage. They sound technical, but the ideas are simple, and understanding them is one of the best ways to decide whether borrowing to invest suits you.
Equity, in plain English
Equity is the part of a property you actually own: what it's worth, minus what you still owe on it. If your home is worth $600,000 and you owe $320,000, you have $280,000 of equity.
How much of it can you use?
Banks won't let you borrow against all of it. They usually lend up to a set percentage of a property's value, commonly around 80%, although it differs between lenders and changes over time. Whatever's left after your mortgage, up to that limit, is your usable equity.
With a $600,000 home and an 80% limit, the bank is comfortable with total borrowing of up to $480,000. You owe $320,000, so about $160,000 is usable.
That usable equity can act as the deposit on a rental, in place of cash. Banks usually want a bigger deposit on an investment property than on a home, commonly around 30% of the purchase price. So $160,000 of usable equity could cover the deposit on a rental of roughly $530,000, before costs.
So what is leverage?
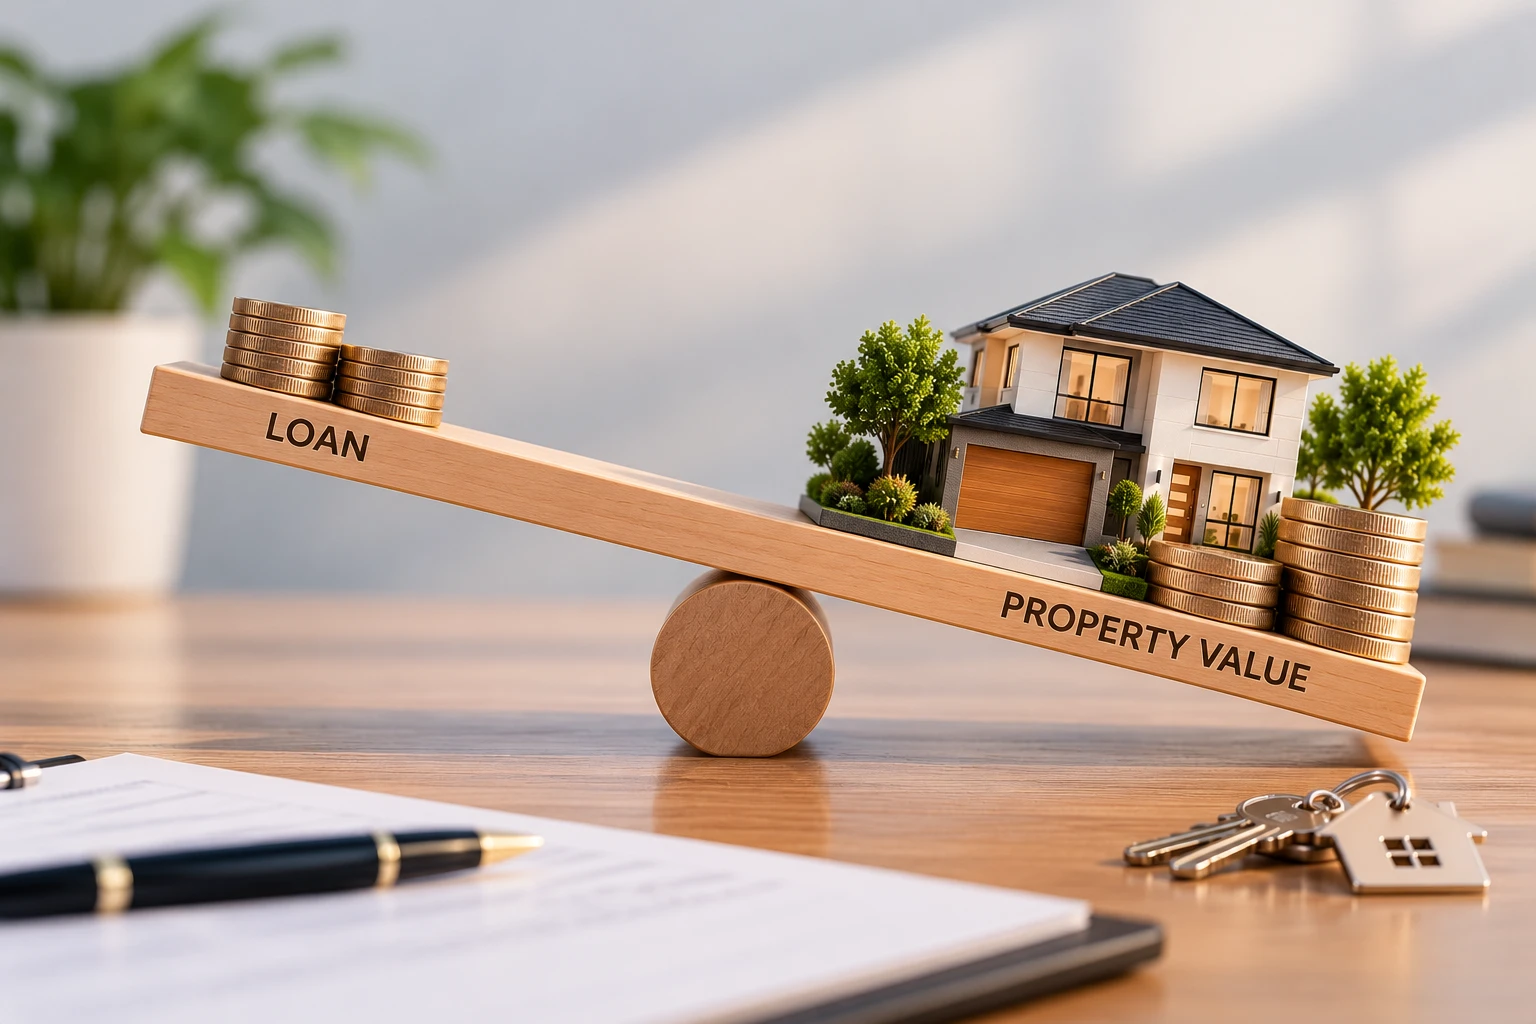
Leverage means using borrowed money to own more property than you could with your own cash alone. Using equity as your deposit is leverage in action: you buy a second property without having to find the deposit in cash.
Here's the example above in full. Try it with your own numbers, or press the button to fill in the example, then move the slider to see what a change in property values does.
Reading the example
You own a $600,000 home and owe $320,000. You buy a $450,000 rental, and the bank lends you the full $450,000. $315,000 is secured against the rental, and the other $135,000 is borrowed against the equity in your home to cover the 30% deposit.
Afterwards you own $1,050,000 of property instead of $600,000, and owe $770,000 instead of $320,000. Your equity is the same, $280,000, because the equity you used is now sitting in the rental.
The difference shows up when values move. If property values rise 5%, your equity grows by $52,500 instead of $30,000. That's the pull of leverage: the same market move, applied to more property.
It cuts both ways. If values fall 5%, you lose $52,500 of equity instead of $30,000.
The other side of borrowing
Leverage can make good outcomes bigger, and it does the same to bad ones. It helps to keep these in mind:
- Values can fall, and you still owe the same. A loan doesn't shrink when the property's value does.
- Interest is a real, ongoing cost. At 5%, borrowing the extra $450,000 costs about $22,500 a year before the property has earned a cent. The rent calculator on my investing page shows how that compares with the rent.
- Interest rates can move. A 1% rise on $450,000 adds about $4,500 a year.
- Equity isn't the only test. Lenders also look at your income and whether you could afford the repayments, and that often sets the real limit.
- More than one property is at stake. If you borrow against your home to invest, both are tied to the loan.
Quick tip
Before you borrow against your home to invest, talk to a mortgage adviser or your bank about your own situation. Equity is only one part of what a lender looks at.
Working out whether it stacks up
Equity tells you what you could borrow, not whether a property is a good buy. For that, look at the numbers behind the property itself: its gross and net yield and the expenses you'll need to allow for.
Happy to talk through what you're weighing up, and what's around in Southland at the price point you have in mind.
This is general information only, not financial, tax or lending advice. Lending criteria differ between lenders and change over time. Speak to a mortgage adviser or accountant about your own situation.